

Xoom: Send Money & Transfer
4.8

When I look at a money-transfer app, I care less about a long feature list and more about one practical question: can I send money to someone abroad without turning the process into a confusing chore? Xoom: Send Money & Transfer is built around that exact job. It is a finance app from Xoom, a PayPal Service, and its main appeal is the ability to send money from the phone to Mexico, India, and many other destinations.
I tested it with the mindset of someone helping family in another country, not someone comparing financial products on paper. My overall impression is that Xoom is most useful when the recipient needs a straightforward international transfer and both sides are comfortable checking the details before confirming. It feels more focused than a general banking app, which is helpful when speed and clarity matter, although the final value of a transfer depends heavily on the destination, delivery method, exchange rate, and any applicable fee shown during the transaction.
One focused job: making an international transfer less stressful
The strongest part of Xoom: Send Money & Transfer is its narrow purpose. Instead of making me navigate a full bank account, investments, cards, and budgeting tools, it puts the overseas transfer at the center. That focus matters when I am sending support to a relative, paying someone in another country, or moving money for a specific personal reason.
The service covers Mexico, India, and another 145 countries, so it is designed for more than one migration corridor. Still, I would not assume that every destination works in exactly the same way. International transfers are shaped by local banking systems, recipient options, currency conversion, and delivery rules. I always treat the destination selection as the first important checkpoint rather than assuming that a method available in one country will appear everywhere.
The app is free to download, which removes the first barrier for someone who wants to try it. That does not mean every transfer is free. The meaningful cost is the one displayed for the particular transaction, along with the exchange rate and the amount the recipient will receive. I would never judge the service by the download price alone; I would review the complete confirmation screen before sending anything.
That distinction is especially important for smaller transfers. A fee or less favorable conversion can have a noticeable effect when the amount is modest. For a larger transfer, the exchange rate can matter more than a small visible charge. Xoom makes sense when I want the convenience of a dedicated transfer workflow, but I still compare the final recipient amount with my bank or another remittance service before committing.
What the focused design changes for everyday users
In my experience, a dedicated transfer app reduces the mental load. I can approach the task as a sequence: choose the destination, enter the recipient information, select the available delivery option, review the amount, and confirm. That is easier than trying to piece together an international payment through a standard bank interface that may be designed primarily for domestic activity.
The practical benefit is not just fewer screens. It is having the important questions in front of me at the right time: how much am I sending, what currency is involved, how much should arrive, and where will the recipient collect or receive it? I find that structure valuable because transfer mistakes are usually caused by rushing through details rather than by not knowing how to press the final button.
There is also a useful psychological advantage to a recognizable service. Xoom has a 4.8 average from around 363 thousand ratings, and it has passed five million installs. Those figures do not guarantee that every transfer will be perfect, but they suggest that the app is familiar to a substantial user base. I still verify every transaction myself, especially when the recipient’s name or account details are involved.
How I would use it in practice
I would begin by installing the app and setting aside a few minutes when I am not distracted. A transfer is not the kind of task I like doing while walking through an airport or answering messages. The recipient’s details need to match the chosen delivery method, and I want time to read the amount and conversion information rather than tapping through habit.
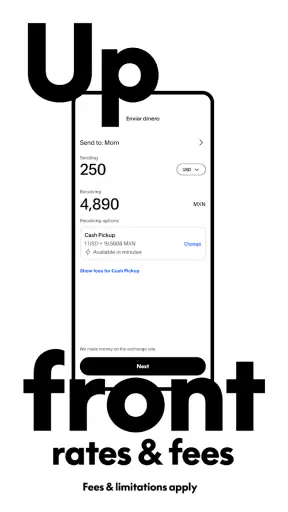
After opening the app, I would select the receiving country first. This is more than a location preference: it determines what transfer paths may be available and what information the recipient requires. I would then enter the amount and inspect the result in the receiving currency. The number that matters most to my family member is not simply what leaves my account; it is what they can actually receive.
Before confirming, I would pause on the review screen and check four things: the sender amount, the recipient amount, the exchange rate, and the total cost. I would also check the recipient’s name character by character. A saved contact can make future transfers easier, but it can also make an old mistake easier to repeat. My tip is to compare the recipient details with a recent message from the person every time the transfer is important.
For a recurring family payment, I would keep a simple note outside the app with the date, amount sent, and amount received. That gives me a personal record for budgeting and helps identify whether a change came from the amount I entered, the conversion, or the transfer cost. I would not rely on memory, particularly if I send money in different currencies.
A realistic family-support example
Imagine that I live in the United States and need to send money to a relative in Mexico for a household expense. I would open Xoom, choose Mexico, enter the amount I can afford, and then focus on the amount displayed for the recipient. If the app presents more than one way for the money to arrive, I would ask my relative which option is genuinely convenient for them rather than selecting the first one.
That conversation is an often-overlooked part of the workflow. A transfer that looks fast from my side may be inconvenient if the recipient has to travel, lacks access to a particular account, or prefers another way of receiving funds. The best option is not automatically the one with the shortest label. It is the one that fits the recipient’s daily reality.
I would send a small test amount the first time I use a new recipient or delivery route. That is not because I expect a problem; it is a sensible way to confirm that the details and receiving method are correct before sending more. Once the recipient confirms receipt, future transfers become less stressful, though I would still review the confirmation information each time.
For India, I would follow the same principle but pay close attention to the local receiving details requested by the app. I would not copy information from an old transfer without checking it. People change accounts, phone numbers, and preferred receiving methods, and an international transfer is a poor place to assume that yesterday’s information is still current.
Questions I would answer before sending
Can I use it for any country? The service is intended for Mexico, India, and 145 other countries, but the exact options are destination-specific. I would select the country and inspect the available route before promising a recipient how the money will arrive.
Is downloading it the same as making a free transfer? No. The app itself is free, while the transaction can involve a displayed fee and a currency conversion. My advice is to judge the complete recipient amount, not just the headline transfer amount.
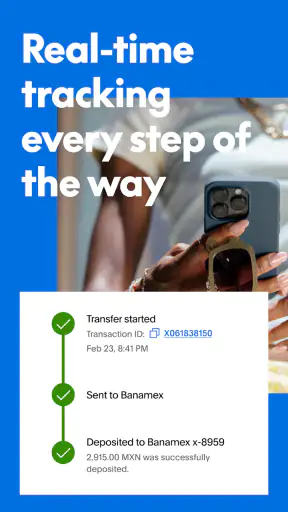
How quickly will the recipient get the money? I would avoid giving a blanket answer. Delivery depends on the selected route and destination. The app’s transaction details are more useful than a general expectation, and I would tell the recipient what the confirmation says rather than promising an exact arrival time.
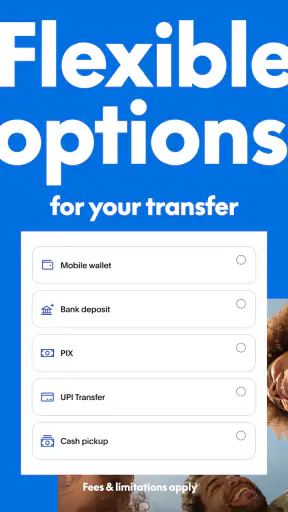
Do I need a bank account on the receiving side? Not necessarily in every situation, because the available receiving method can vary by destination. I would let the app show the choices for the selected country and then confirm that the recipient can actually use the chosen option.
Is it suitable for business payments? I would be cautious. Xoom can be convenient for personal remittances and one-off international support, but businesses may need invoices, accounting records, approval controls, and a different level of payment administration. For those needs, a business-focused service or bank process may be a better fit.
Where the convenience has real limits
The first trade-off is cost transparency. Xoom shows the relevant transfer information during the process, but the price of sending money is not one universal number. It changes with the destination, currency, amount, and route. That means I cannot decide whether it is the cheapest option from the app name alone. I compare the final amount received with at least one alternative when the transfer is not urgent.
The second trade-off is that convenience can encourage speed over checking. A clean interface makes it easy to move quickly, but international transfers require careful attention. A misspelled name, outdated account detail, or unsuitable receiving method can create friction that no attractive design can remove. I prefer to treat the confirmation screen as a mandatory review, not a formality.
The third limitation is that Xoom is not a replacement for a complete personal finance system. It is not where I would expect to manage my monthly budget, track every bill, or plan investments. Its value comes from solving a cross-border sending task. If my main need is domestic payments or everyday banking, my existing bank app may be simpler because the money is already there and the recipient is likely using the same local system.
There is also a difference between being able to send money and being able to resolve every situation instantly. If a transfer needs clarification, I may have to provide accurate information and wait for the relevant process to complete. I would keep confirmation details and avoid deleting messages or records until the recipient confirms the funds arrived. That small habit makes follow-up much easier.
Privacy and account security deserve practical attention too. I would use a strong device lock, avoid sending personal financial details through casual chat, and check that I am using the official app before entering information. The app is rated for Everyone, but that age label does not mean every financial decision is suitable for a child. Adults should remain responsible for the account, the recipient details, and the transfer decision.
How it compares with the usual alternatives
Compared with a traditional bank transfer, Xoom may feel more direct for remittances because the workflow is built around sending money internationally. A bank can be preferable when I already have a strong relationship with it, need a detailed account record, or want all activity in one financial dashboard. The bank may also be more comfortable for a large, formal payment, depending on its own process.
Compared with cash-based remittance services, the app offers the convenience of starting the process from a phone. That is useful when I cannot visit a location during opening hours. On the other hand, cash pickup can be the better choice for a recipient who does not use online banking or wants physical cash. The correct comparison is not app versus cash in the abstract; it is which receiving method the person can use safely and easily.
Compared with digital wallets, Xoom is more appealing when the sender and recipient are in different countries and do not share the same wallet ecosystem. A wallet can be smoother for people already using one platform locally, especially for frequent small payments. I would choose Xoom when the international route and recipient access matter more than keeping everything inside one wallet.
Compared with specialist currency-transfer services, Xoom may win on familiarity and a simple remittance-oriented flow. A specialist can sometimes be more attractive for larger recurring transfers where exchange-rate differences deserve close analysis. I would not assume that one service is best for every amount. For occasional family support, simplicity may justify Xoom; for regular high-value transfers, comparison becomes more important.
Who gets the most value from it
I think Xoom is a strong candidate for people who regularly support relatives abroad, especially when the recipient lives in one of the countries served and wants a practical receiving option. It is also useful for someone who sends money only occasionally and does not want to learn a complicated banking procedure each time.
It can suit travelers who need to help someone at home while away, provided they have reliable access to their account and enough time to review the transaction. It may also help families coordinate an urgent expense across borders, although I would still avoid promising instant delivery until the app gives a clear expectation for that specific route.
The people who benefit most are not necessarily those seeking the absolute lowest possible cost. They are the users who value a dedicated mobile workflow, broad country coverage, and a familiar service enough to accept that each transaction must be evaluated on its own terms. For them, the reduction in hassle can be meaningful.
I would suggest looking elsewhere if the transfer is domestic, if both people already use the same local payment wallet, or if the main goal is detailed financial management. I would also compare alternatives carefully for a large recurring payment, because a small exchange-rate difference can become important over time. Xoom is a focused tool, not a universal answer to every money problem.
My practical verdict after using the workflow
Xoom succeeds because it concentrates on the moment that matters: getting money from one country to another with fewer unnecessary decisions. The app is free, works in the finance category, and its current version is 10.11.0 for operating systems from version 10 onward. The long-running release history, beginning on August 8, 2012, and the large user base make it feel established rather than experimental.
What I appreciate most is the ability to start from the recipient’s country and work toward a clear delivery choice. What I like least is that convenience does not remove the need to compare costs or verify details. The app can streamline the transfer, but it cannot decide whether the conversion is good enough for my particular amount or whether the recipient’s preferred route is practical.
My recommendation is simple: use it when you need a focused international remittance tool, but make the confirmation screen part of your routine. Check the recipient, receiving method, total cost, exchange rate, and expected delivery information. If those details work for your situation, Xoom can be a genuinely convenient way to send support across borders. If cost optimization, formal business controls, or everyday domestic banking matters more, another option may serve you better.
The best reason to choose Xoom is not that it promises to make every transfer identical; it is that it gives a clear, phone-based path for a task that often feels complicated. Used with a careful final review and a quick comparison when the amount is significant, it is an app I would comfortably recommend to a friend sending money internationally.
4.8
30.30K Reviews
Pros
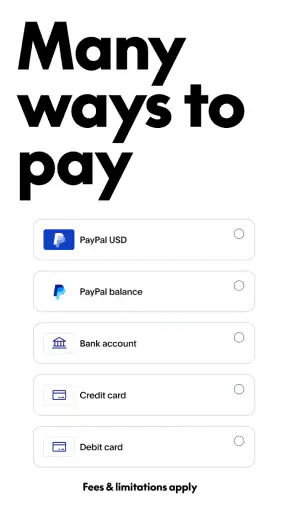
- Fast transfers to many countries and supported payment methods.
- Clear exchange rates and transfer fees shown before confirmation.
- Recipients can often receive funds in local currency.
- Transfer tracking helps you monitor delivery progress.
- Useful cash-pickup options for recipients without bank accounts.
Cons
- Availability and fees vary significantly by destination country.
- Exchange rates may be less competitive than specialist currency services.
- Some transfers require identity checks and additional documentation.
- Cash pickup depends on local agent availability and opening hours.
- Delivery times can be delayed by weekends
- holidays
- or compliance reviews.


